Dublin Property Market Update, November 2026: House Prices, Rents and Rental Yields
The Dublin property market is cooling, not crashing. Dublin house prices are still rising, but at the slowest pace in nearly three years, rents have steadied after a record jump in spring, and borrowing costs are heading the wrong way. Here is where the Dublin property market stands for first-time buyers, home sellers, landlords and renters, with practical advice for each.
Dublin house prices: growth is slowing
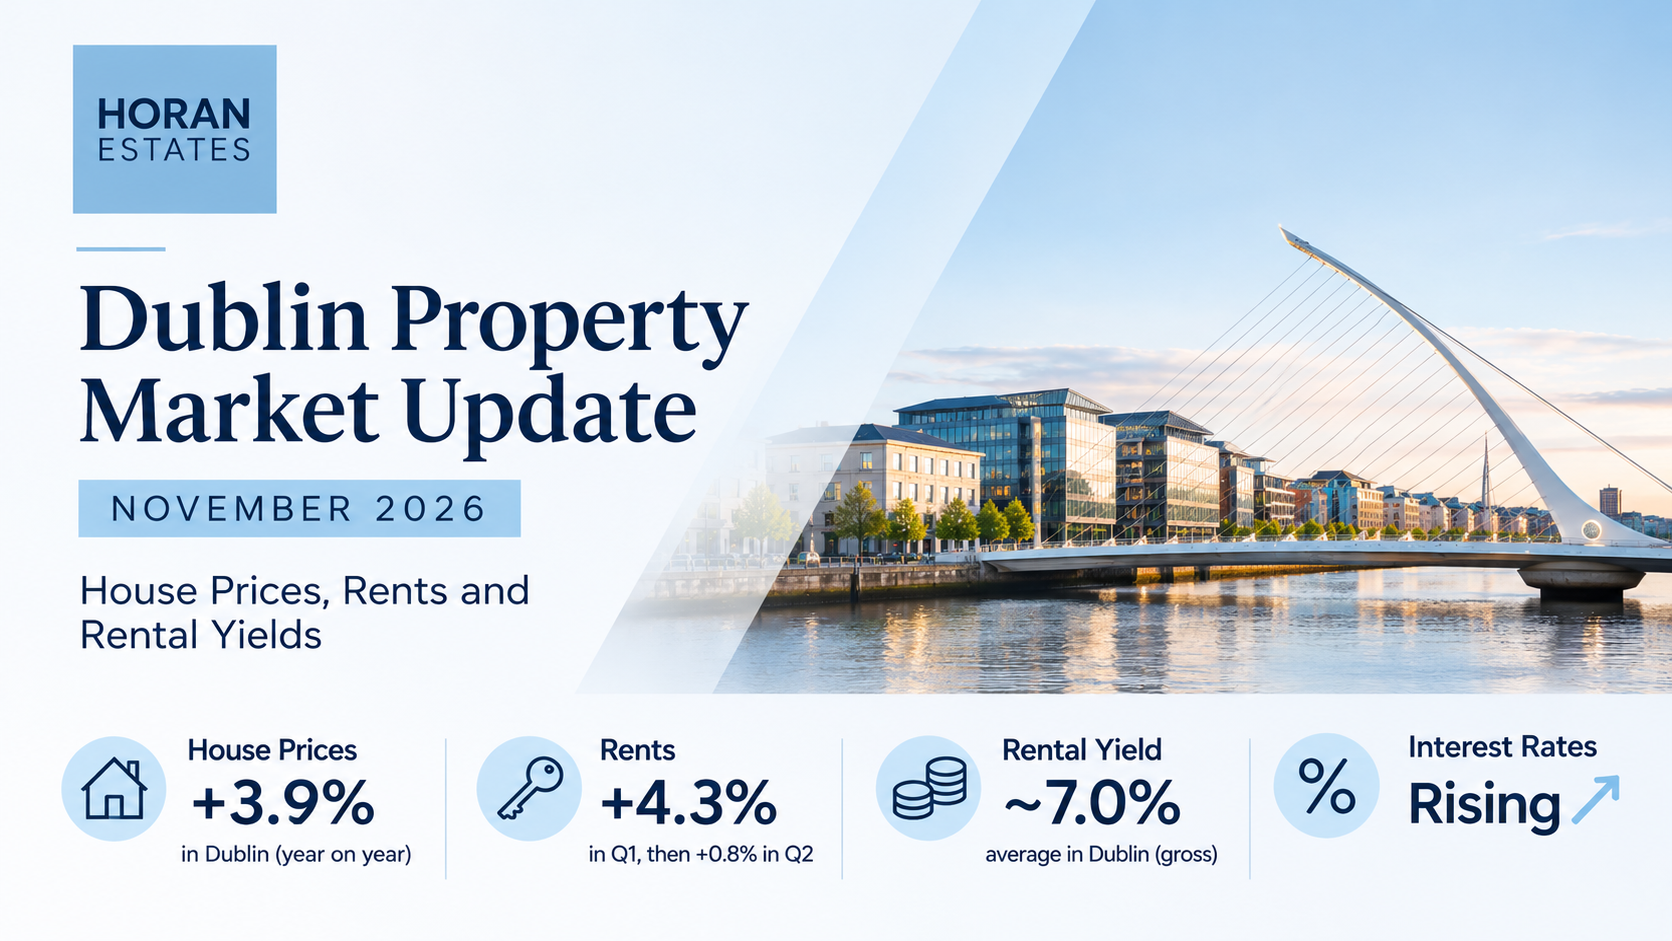
The latest CSO figures (August 2026) show Dublin house prices up 3.9% on a year earlier, down from 4.5% in July. Nationally, prices rose 5.1%, the slowest annual growth since late 2023, and prices outside Dublin (up 6.2%) are now rising faster than in the capital.
In plain English: a Dublin home that sold for €500,000 a year ago would typically be worth about €19,500 more today. Prices are still going up, but the climb is flattening out.
• Houses: up 3.3%. Apartments: up 5.7% (CSO)
• Median price over the 12 months to August 2026: €500,000 (CSO)
• Average asking price for a three-bed semi-detached house: €635,000 (Daft.ie, Q3 2026)
Asking prices are slowing too. Daft.ie reports Dublin asking prices up 2.7% on a year ago, while nationally the prices buyers actually paid rose just 0.8%. When asking prices rise faster than sale prices, it can mean buyers are negotiating harder. Bank of Ireland forecasts national price growth of around 4% in 2026.
Dublin rents: a record jump, then a pause
New rental rules from March 2026 let landlords reset the rent to the market rate when a tenancy ends. Daft.ie reports that Dublin rents jumped 4.3% in the first quarter, a record, then rose just 0.8% in the second. In plain English: 4.3% on a rent of about €2,300 is roughly €100 more a month.
Supply is the problem. The number of homes to rent in Dublin is about a third below the 2015-2019 average. The RTB (Residential Tenancies Board) reports an average rent of €2,335 a month for new Dublin tenancies, against €1,960 for existing tenancies.
Rental yields in Dublin: still attractive, but read the small print
Global Property Guide puts average gross rental yields in Dublin at around 7%. In plain English: yield is the yearly rent as a percentage of the property's price, so 7% means €7,000 a year for every €100,000. Gross yield is before tax, repairs, fees, empty periods and mortgage costs. Net yields are typically 1.5 to 2 percentage points lower, and rising mortgage rates squeeze landlords with loans first.
Supply: completions are up nationally, but Dublin lags
Ireland completed 26,833 new homes in the first nine months of 2026, up 10.6% on last year, and Deloitte says 2026 is on track for the most completions since 2008. That is real progress, but still well short of the 50,000 or more homes a year experts say are needed. In the second quarter, completions in the Dublin region fell 16.4%.
The economy and borrowing costs
• Interest rates: the European Central Bank (ECB), which sets interest rates for the euro area, raised rates in June and September to fight inflation driven by higher energy prices. Brokers warn that further rises before Christmas are possible. Tracker mortgages, whose rates move automatically with the ECB's, feel changes first.
• Inflation: everyday prices in Ireland were around 3.4% to 3.7% higher than a year earlier in August, well above the ECB's 2% target.
• Jobs: unemployment was 5.0% in September, up slightly on a year ago.
What this means for buyers, sellers, landlords and renters in Dublin
Advice for first-time buyers in Dublin
Slower price growth and more homes for sale give first-time buyers a little more breathing room than a year ago. Some practical steps:
• Update your mortgage approval in principle before you start viewing. This is the bank's written confirmation of roughly how much it will lend you. With interest rates rising, lenders can change their pricing, so a stale approval can leave you short.
• Test your budget against higher repayments. Ask your broker what your monthly payment would be if mortgage rates rise again, and only commit to a figure you could still manage.
• Budget beyond the deposit. Legal fees, a survey, stamp duty on second-hand homes and moving costs all add up.
• Check what State help you qualify for. Budget 2027 raised the Help to Buy grant for new homes by €5,000, from €30,000 to €35,000. Stamp duty for first-time buyers of second-hand homes was not changed. Confirm your eligibility with Revenue and your mortgage broker before you bid.
• Don't stretch to the very top of your budget. With prices rising more slowly, there is less pressure to overpay just to get on the ladder.
Advice for selling your home in Dublin
In a slower market, buyers compare homes more closely, so how you price and present your home matters more than it did a year ago.
• Price to the market, not to hope. Look at what similar homes in your area have actually sold for (the Property Price Register lists them), not just what they were advertised at.
• Get a professional valuation from a local estate agent before choosing an asking price. Homes priced in line with recent sales are still selling; overpriced ones tend to sit and then need a price cut.
• Have your paperwork ready. Your BER certificate, title documents and any planning permissions should be in order before you list, as delays can cost you a sale. Buyers are also paying more attention to running costs while energy prices are high.
• Line up your own move. If you are buying as well as selling, speak to your lender early so your sale and purchase timelines fit together.
Advice for landlords and property investors
Dublin rents are high and tenant demand is strong, but the sums are tighter than the headline rent suggests.
• Work out your net yield, not your gross yield. Subtract tax, repairs, management fees, insurance and gaps between tenants from your rental income before judging a property.
• Stress-test your mortgage. If you have a tracker or variable-rate loan, check that the rent still covers the repayments if the ECB raises rates again.
• Know the rental rules. The March 2026 changes let landlords reset the rent to the market rate when a tenancy ends, but registration with the Residential Tenancies Board (RTB) and notice requirements still apply. Get advice before ending a tenancy.
• Compare locations. Global Property Guide puts average gross yields in Cork (8.33%) above Dublin (7.00%), and Daft.ie says rents elsewhere in Ireland have risen faster than in the capital. A Dublin address is not automatically the best return.
• Keep good tenants. A property that stays let at a fair rent often beats a higher rent with months of vacancy in between.
Advice for renters in Dublin
With so few homes available to rent, preparation helps.
• Be ready to move quickly. Have references, proof of income and your deposit ready before you start viewing.
• Claim what you are owed. Budget 2027 raised the rent tax credit by €150, to €1,150 for a single person and €2,300 for a jointly assessed couple. Check your eligibility on Revenue's website.
• Know your rights. The RTB's website explains rent rules, deposits and what to do if there is a dispute.
Dublin property market FAQs
Are house prices in Dublin going to fall?
There is no sign of a fall so far. Dublin prices are still up 3.9% on a year ago, just by less than before. Rising interest rates and tight housing supply are the two things to watch, and nobody can predict either with certainty.
What is the average rent in Dublin?
The RTB's latest figures put the average rent at €2,335 a month for new Dublin tenancies and €1,960 for existing tenancies.
Will mortgage rates in Ireland go up again?
Several brokers expect at least one more rise before Christmas, but it will depend on inflation. Speak to a mortgage broker about fixing your rate.
Is buy-to-let in Dublin still worth it?
It can be, but it depends on the property, the location and how you finance it. Gross yields average around 7%, but after costs and higher mortgage rates the real return is lower, so run the numbers on net yield first.
Is now a good time to buy or sell in Dublin?
It depends on your own circumstances. Slower price growth gives buyers more room to negotiate, and realistic pricing is the key for sellers. A local estate agent can tell you how your area and property type are performing.
This article is general information, not financial, tax or legal advice. Speak to a qualified adviser about your own situation.
Thinking of buying, selling or letting property in Dublin? Contact Horan Estates for a valuation or rental appraisal.